
Will My Insurance Company Pay For A New Roof in Colorado?
Colorado's homeowners insurance market has changed substantially in recent years, particularly when it comes to roof coverage. Percentage-based wind and hail deductibles have become more common, some carriers have shifted from replacement cost to actual cash value coverage, and insurers increasingly consider repairs before approving a full roof replacement.
What that means for you depends on your policy, the age of your roof and your home's insured value. Understanding those details before you have roof damage can help you avoid surprises when it is time to file a claim.
Whether your insurance company pays for a new roof in Colorado depends entirely on your specific policy type, your deductible, and the severity of the storm damage. Due to recent market shifts, many Colorado insurers now favor partial repairs over full replacements, or pay out based on your roof's depreciated Actual Cash Value (ACV) rather than its full Replacement Cost Value (RCV).
Key Takeaways
- Colorado homeowners face higher wind and hail deductibles than in previous years, and many are now percentage-based rather than flat dollar amounts.
- Your policy may cover your roof's actual cash value rather than its full replacement cost, which affects how much you receive after a claim.
- Insurers may approve a repair rather than a full replacement, depending on the scope of the damage.
- Review your declarations page and talk to your insurance agent to understand what your policy covers before a storm hits.
How Has Colorado's Homeowners Insurance Coverage Changed?
Colorado homeowners insurance coverage has shifted dramatically toward higher percentage-based deductibles, actual cash value (ACV) roof policies, and repair-first claim settlements. This shift comes after years of historic hail losses across the state, combined with a March 2026 federal policy change allowing lenders to back loans with depreciated roof coverage rather than full replacement costs.
Some contractors also offered to waive homeowners' deductibles to win the work. Waiving an insurance deductible is illegal in Colorado.
After years of losses in hail-prone markets, insurers began changing how they price and settle residential roofing claims. In March 2026, the Federal Housing Finance Agency announced that Fannie Mae and Freddie Mac would no longer require full replacement cost coverage on roofs for federally backed loans.
Lenders can now accept policies that cover only the actual cash value of a roof, meaning its value after depreciation rather than the full cost of replacement.
For Colorado homeowners, the important thing is to know what your current policy actually covers. Higher deductibles, depreciation-based payouts, and repair-first claim approaches can all affect what you pay after a storm.
What Is the Difference Between a Flat Deductible and a Percentage Deductible?
Not every deductible works the same way.
- Flat Deductible: A fixed, static dollar amount (e.g., $1,000) paid out-of-pocket regardless of the home's total value.
- Percentage Deductible: A variable out-of-pocket cost calculated as a direct percentage (typically 1% to 5%) of your total dwelling coverage limit, not the cost of the roof repair itself.
Many homeowners policies include a separate percentage deductible for wind and hail events.
| Home's Insured Value | 1% Deductible | 2% Deductible | 3% Deductible | 5% Deductible |
|---|---|---|---|---|
| $300,000 | $3,000 | $6,000 | $9,000 | $15,000 |
| $500,000 | $5,000 | $10,000 | $15,000 | $25,000 |
| $600,000 | $6,000 | $12,000 | $18,000 | $30,000 |
On a home insured for $500,000, a 2% hail deductible is $10,000. On a $700,000 home, the same deductible is $14,000.
If you have not reviewed your policy recently, check your declarations page. Look for a line labeled "Wind/Hail Deductible" or "Named Storm Deductible."
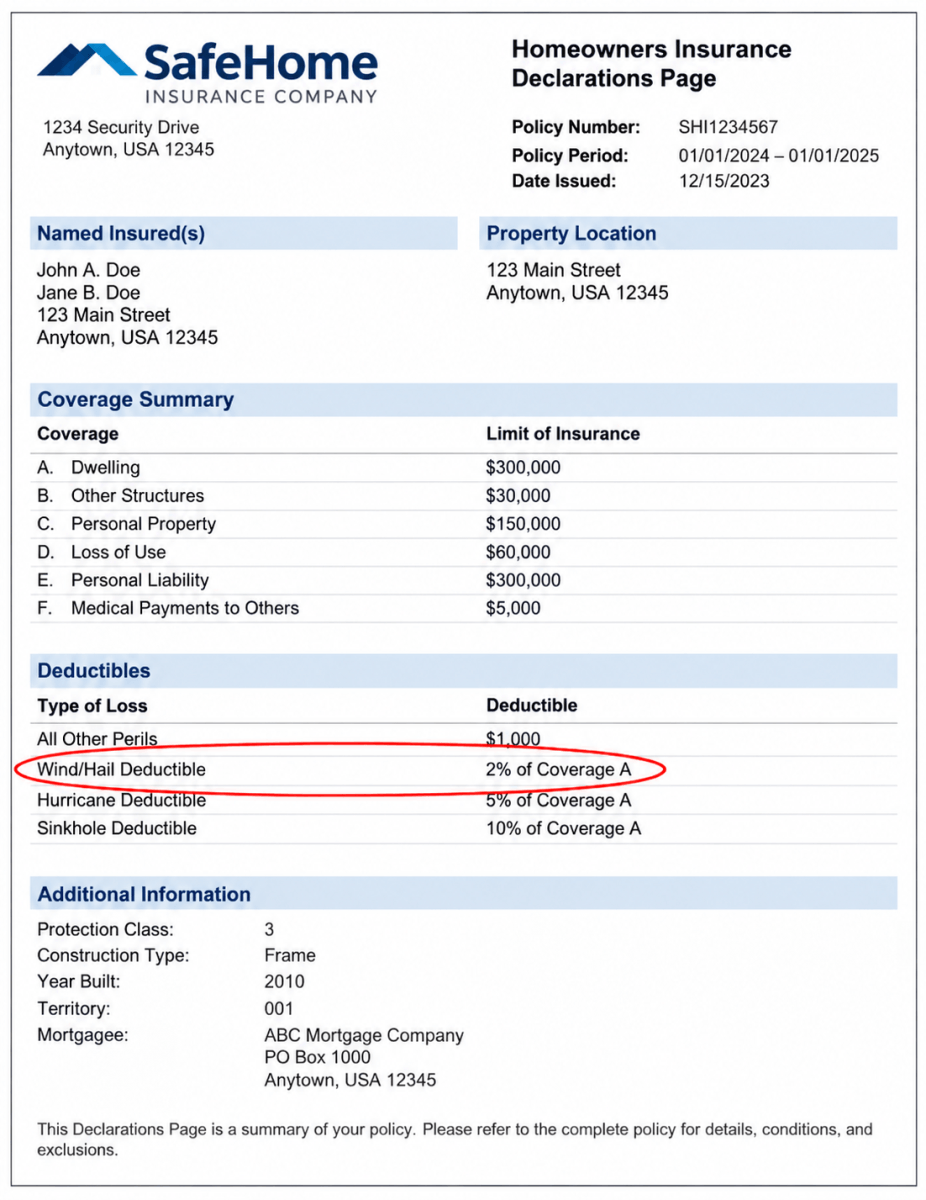
If you are unsure what applies to your home, ask your insurance agent to explain your current wind and hail deductibles.
What Is the Difference Between Replacement Cost Value (RCV) and Actual Cash Value (ACV)?
Your deductible is only part of the equation. The type of roof coverage you carry also affects how a claim is paid.
Replacement Cost Value, or RCV, generally covers the cost to repair or replace damaged roofing with new materials of like kind and quality. Actual Cash Value, or ACV, pays the replacement cost minus depreciation. If an older roof has depreciated significantly, the insurance payment may be substantially less than the actual cost of replacement, and the homeowner is responsible for the remaining cost.
That means two homeowners with similar storm damage may receive very different claim payments depending on their policies. Reaching out to your insurance agent to review your policy is the best way to understand what coverage you have and how much you will be responsible for in the event of a claim.
Our post on what homeowners should understand before filing an insurance claim explains these coverage types in more detail.
Can My Insurance Company Pay for a Repair Instead of a Full Roof Replacement?
Insurers are increasingly evaluating whether damaged areas can be repaired before approving a complete roof replacement. When damage is partial or localized, a repair may be the proposed claim settlement rather than a full reroof.
Some policies also contain language that affects when an insurer is obligated to repair or replace damaged roofing.
If you believe the damage to your roof is more extensive than what was identified during the insurance inspection, documentation is important. A licensed, reputable roofing contractor can inspect the roof, document visible damage and communicate those findings during the claim process.
For more information, see our overview of roofing insurance and coverage changes.
What Should Colorado Homeowners Do About Their Roof Insurance?
Review your policy. Check your wind and hail deductible and determine whether your roof has RCV, ACV or another type of coverage.
Talk to your insurance agent. Ask how your current policy handles roof damage, what deductible applies to wind and hail claims, and how a claim would be paid.
Know the condition of your roof. Understanding its age and current condition can help you plan for maintenance and future replacement. If you need a roofing professional, you can find a licensed, vetted CRA member contractor through the Colorado Roofing Association's member directory.
Plan for your deductible. If you have a high wind or hail deductible, consider building that amount into your household's emergency or home maintenance savings.
Colorado homeowners cannot control when the next hailstorm hits. They can know what their insurance covers and what they may be expected to pay before it happens.
Frequently Asked Questions
Will my insurance company pay for a full roof replacement after a hailstorm?
Not always. Whether insurance covers a full replacement depends on your policy type, your deductible, the age of your roof and the extent of the damage. Some policies cover full replacement cost, while others pay only the actual cash value after depreciation. Insurers are also increasingly approving repairs rather than full replacements when damage is partial or localized. Reviewing your policy and talking with your insurance agent before a storm hits is the best way to know what to expect.
How has Colorado's homeowners insurance coverage changed in recent years?
Insurers operating in Colorado have shifted toward higher wind and hail deductibles, more actual cash value roof policies, and repair-first claim settlements. In March 2026, the Federal Housing Finance Agency also announced that Fannie Mae and Freddie Mac would no longer require full replacement cost coverage on roofs for federally backed loans, which means lenders can now accept policies that cover only a roof's depreciated value.
What is the difference between a flat deductible and a percentage deductible on a roof claim?
A flat deductible is a fixed dollar amount you pay before insurance coverage applies. A percentage deductible is calculated using your home's insured value, not the cost of the repair. A 2% wind and hail deductible on a home insured for $500,000 is $10,000 out of pocket before coverage applies. Check your declarations page and ask your insurance agent if you are unsure which type you have.
How do I know if my roof is covered under ACV or RCV?
Check your declarations page and policy documents for language specifying replacement cost or actual cash value coverage. If it is unclear, contact your insurance agent and ask directly how your roof is covered and what you would receive in the event of a wind or hail claim.
Can my insurer pay for a repair instead of a full replacement?
Yes. Depending on your policy and the extent of the damage, an insurer may determine that damaged areas can be repaired rather than replacing the entire roof. If you believe the damage is more extensive than what was identified during the insurance inspection, a licensed roofing contractor can document the full scope and communicate those findings during the claim process.
What happens to withheld depreciation under an RCV policy after I complete repairs?
Under many RCV policies, the insurer withholds recoverable depreciation from the initial payment. After the covered work is completed, you submit the required invoices and documentation so the recoverable amount can be released, subject to the terms of your policy. Ask your insurance agent to walk you through how this works under your specific coverage.
Is it illegal for a Colorado roofing contractor to waive my deductible?
Yes. Waiving insurance deductibles is illegal in Colorado. Be cautious of any contractor who offers to cover, waive or otherwise eliminate your required deductible.
How much should I set aside to cover a roof deductible?
Start with your actual wind and hail deductible. If it is percentage-based, multiply your Coverage A limit by the deductible percentage to find the amount you could be responsible for before coverage applies. Use that figure as a savings target so you are prepared if a storm causes damage.